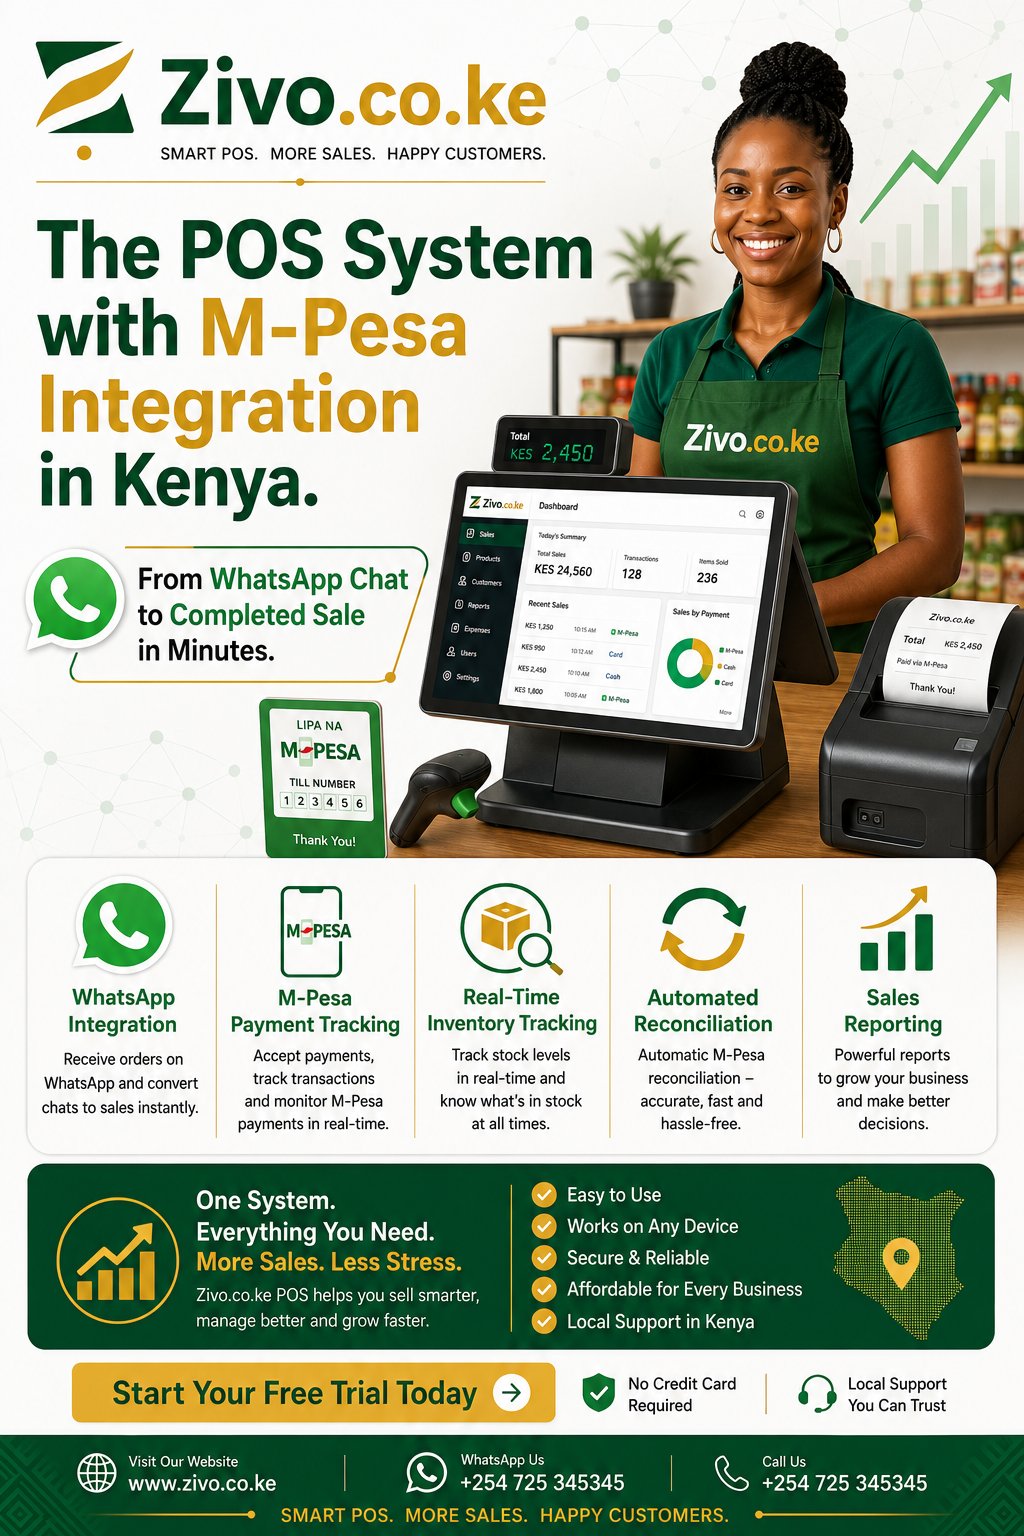
The M-Pesa Payment Integration in Kenya is the technical bridge that connects your business to the country’s most powerful payment rail. For Kenyan business owners, M-Pesa Payment Integration in Kenya means real-time collections, automatic reconciliation, and cleaner operations. Zivo.co.ke has built its entire platform on this foundation.
M-Pesa moves over 100 million transactions daily and peaks at 6,000 transactions per second. About 25% of all M-Pesa transactions now flow through APIs. That number keeps climbing.
If your business is not integrated, you are handling money the hard way. Manual reconciliation. Screenshot verification. Month-end guesswork. M-Pesa Payment Integration in Kenya removes all of that.
Zivo.co.ke is the practical answer. It handles M-Pesa Payment Integration in Kenya so your team does not have to. It connects payments to invoices, invoices to jobs, and jobs to completion.
One flow. One record. No gaps.
Why Zivo.co.ke is the M-Pesa Payment Integration in Kenya
Kenya’s digital payment landscape changed forever when Safaricom launched Daraja in 2017. The name means “bridge.” It cut integration timelines from over 60 days to something much faster.
Before Daraja, connecting to M-Pesa was slow and painful. Businesses waited months. Developers struggled with unclear documentation.
Daraja solved that. It gave developers a clear path. It gave businesses a way to automate payments.
Today, Daraja 3.0 is live. It is built on cloud-native architecture. It delivers higher uptime, stronger security, and faster rollouts. The Daraja ecosystem now includes over 66,000 integrations and more than 105,000 developers.
The M-Pesa Payment Integration in Kenya is no longer a luxury. It is the standard. Businesses that integrate see faster settlements and cleaner books.
Zivo.co.ke makes this integration practical. It handles the technical complexity. It connects payments to your entire workflow.
The result is simple. You know your money position at any moment. No guesswork. No month-end panic.
What M-Pesa Payment Integration Actually Means
Let me explain this in plain language.
An API is a messenger. It carries instructions between two systems. Your system says “request payment.” M-Pesa says “payment complete.” The API carries that message back and forth.
M-Pesa Payment Integration in Kenya means your business software talks directly to Safaricom’s systems. No human needs to copy numbers. No one needs to match screenshots.
The Daraja API exposes several endpoints. Most businesses need only one or two.
M-Pesa Express (STK Push) is the most common. The customer enters their phone number. Your system sends a payment prompt to their phone. They enter their PIN. You get a callback.
C2B (Customer to Business) is for offline payments. The customer pays your Paybill or Till directly. You receive webhooks.
B2C (Business to Customer) sends money out. Refunds. Seller payouts. Supplier payments.
Account Balance and Transaction Status are utility APIs. They keep integrations reliable. They tell you your float balance. They query transaction states when callbacks fail.
Zivo.co.ke uses these APIs. The M-Pesa Payment Integration in Kenya from Zivo handles the complexity.
The Real Cost of Not Integrating
Manual payment handling is expensive. It costs time. It costs money. It costs accuracy.
Manual M-Pesa reconciliation eats 4 to 8 hours weekly. Finance staff spend 2 to 3 hours daily matching receipts. That is 30 hours weekly across a small team. Over 120 hours monthly.
At a loaded cost of KES 400 per hour, that is KES 48,000 monthly. Nearly KES 600,000 annually. And that is before counting the errors.
Without M-Pesa Payment Integration in Kenya, a shop leaves 3 to 8 percent of M-Pesa transactions unmatched. For a business collecting KES 1.2 million monthly, a 3 percent leak means KES 36,000 lost every month. Over KES 430,000 a year.
Most Kenyan SMEs lose KES 2,000 to KES 5,000 monthly to reconciliation errors alone. Duplicate entries. Timing mismatches. Lost transaction receipts.
The M-Pesa Payment Integration in Kenya removes this entire category of loss. Payments are captured the moment they arrive. They are matched to invoices automatically. They are recorded permanently.
Your team stops chasing receipts. They start chasing growth.
What Manual Reconciliation Actually Costs
Picture a Nairobi service business with three staff handling payments. Each spends roughly two hours daily on M-Pesa reconciliation. That is six hours daily across the team.
Thirty hours weekly. Over 120 hours monthly.
At a modest loaded cost of KES 400 per hour, that is KES 48,000 monthly burned on work M-Pesa Payment Integration in Kenya should do. Nearly KES 600,000 annually. And that is before counting the errors.
The Screenshot Problem
Screenshots are the silent killer of Kenyan bookkeeping.
A customer pays. They screenshot the confirmation. They send it on WhatsApp. Your staff sees it. They mark the invoice as paid mentally.
Three weeks later, the payment is not in the bank. The customer used a different number. Or the transaction failed. Or the screenshot was for a different invoice.
Now you are chasing money you thought you had. And you have no record to prove otherwise.
Fake M-Pesa SMS scams target traders. Criminals send flawless fake confirmation messages. Anyone who visually checks the message instead of verifying the transaction is at risk.
A proper M-Pesa Payment Integration in Kenya eliminates this entirely. It reads the actual transaction record, not a screenshot. It verifies against the M-Pesa API. It cannot be fooled.
Why Kenyan Businesses Struggle Without Integration
Kenyan SMEs face a payment culture problem. Over 60 percent report payment delays beyond 30 days. The government alone owes suppliers roughly KES 525 billion in pending bills. Some suppliers wait 90 to 180 days. Others wait years.
This creates a cash flow squeeze. Salaries are due monthly. Rent is due monthly. Suppliers want payment within 30 days. KRA wants its share on time.
But money coming in does not follow the same rhythm. It arrives late. It arrives in pieces. It arrives with no clear reference.
The M-Pesa Payment Integration in Kenya must address this reality. It must speed up collections. It must reduce friction. It must remove excuses.
Zivo.co.ke does all three. Invoices go out instantly. Payment instructions are embedded. Reminders are automatic. There is no gap where a customer can say “I forgot” or “I did not receive it.”
When the path to payment is frictionless, collection happens faster. The right M-Pesa Payment Integration in Kenya makes this possible. It is that simple.
How M-Pesa Changed Everything — And Why Software Has Not Kept Up
M-Pesa is a Kenyan success story. It brought financial services to millions. It made money move in seconds. It turned every phone into a bank branch.
M-PESA has surpassed 40 million monthly active customers in Kenya. It contributes 45.6% of Kenya’s service revenue.
But M-Pesa was designed for people. Not for business workflows.
A personal M-Pesa account works fine for one person. It shows a balance. It shows a history. It sends SMS confirmations.
A business needs more. It needs to know which payment belongs to which invoice. It needs to reconcile hundreds of transactions against a ledger. It needs to see failures, reversals, and expiries.
An M-Pesa Payment Integration in Kenya must bridge this gap. It must turn raw M-Pesa data into business intelligence.
Zivo.co.ke does exactly this. The M-Pesa Payment Integration in Kenya reads every payment. It categorises it. It matches it. It reports on it.
Your M-Pesa history becomes a financial dashboard. That is the difference between having money and understanding money.
Key Features That Make Zivo.co.ke the M-Pesa Payment Integration in Kenya
Zivo.co.ke is engineered to be the M-Pesa Payment Integration in Kenya by solving problems local businesses actually face. Here is what it does.
STK Push Payment Requests
This is the core. Zivo.co.ke sends payment prompts directly to customer phones. The customer enters their PIN. The payment is processed.
No manual entry. No screenshots. No waiting for a bank statement.
The M-Pesa Payment Integration in Kenya from Zivo handles this automatically. Your team creates an invoice in the chat. The customer receives a prompt. The system records everything.
Callback Handling and Reliability
Callbacks are not always reliable. Safaricom posts results asynchronously. If your server is slow or behind an aggressive firewall, callbacks never arrive.
Slow or unreliable callback URLs are a common failure point. Callback idempotency matters. Without it, you get duplicate ledger entries.
The M-Pesa Payment Integration in Kenya from Zivo handles this properly. It treats callbacks as authoritative. It prevents duplicates. It has observability built in.
If a callback fails, Transaction Status API queries the state. The system stays reliable.
Invoices Built Inside WhatsApp
The M-Pesa Payment Integration in Kenya must work where customers already are. In Kenya, that is WhatsApp.
Zivo.co.ke lets your team create an invoice inside the chat. You send a payment link. The customer pays via M-Pesa. The M-Pesa Payment Integration in Kenya records everything. The whole transaction lives in one thread.
No switching apps. No copying numbers. No lost context. No “please resend the invoice.”
WhatsApp already handles 20.2 percent of online order placements in Kenya. Meeting customers where they are is essential.
Automated Payment Reminders
Chasing money is uncomfortable. So invoices age. Then they die.
Zivo.co.ke sends polite reminders automatically. Three days before due. On the due date. Three days after. The M-Pesa Payment Integration in Kenya handles it. Your relationships stay intact.
Live Cash Position Visibility
You cannot manage what you cannot see. Zivo.co.ke shows your cash position live. Money in. Money out. Money expected.
You spot shortfalls before they bite. You spot surplus before it sits idle. Every decision gets sharper.
Approval Chains for Outbound Payments
Not every payment should leave without a check. Zivo.co.ke lets you set approval rules.
A KES 5,000 supplier payment may need one signature. A KES 500,000 payment may need two. The M-Pesa Payment Integration in Kenya routes each request correctly. It records every decision.
Job Assignment After Payment
Here is a feature most payment tools ignore. What happens after money arrives?
For service businesses, payment is only step one. The job still needs doing. Zivo.co.ke assigns that job the moment payment clears.
Nothing gets forgotten. Nothing gets double-charged. Nothing sits in limbo.
How Zivo.co.ke Delivers M-Pesa Payment Integration Through Workflow Automation
Let me walk through a real scenario. Step by step.
Step One — The Customer Enquiry
A customer messages your business on WhatsApp. They want a service. Your team responds.
This is where most businesses start. It is also where most businesses lose track.
Step Two — The Invoice
Your team quotes a price. The customer agrees. Your team creates an invoice in the same chat. They send it.
The invoice has a payment link. It has the amount. It has the due date. It has your business details. It looks professional.
Step Three — The Payment Request
The customer clicks the payment link. Your system calls Daraja. M-Pesa pushes a prompt to the customer’s phone.
This is the M-Pesa Payment Integration in Kenya in action. The customer enters their M-Pesa PIN. The payment is processed.
Step Four — The Callback
Daraja sends a callback to your system. The payment is confirmed. The invoice is marked as paid.
Zivo.co.ke handles this automatically. It verifies the callback. It matches the payment to the invoice. It records everything.
If the callback fails, Transaction Status API queries the state. The system stays reliable.
Step Five — The Job
Here is where Zivo.co.ke goes beyond other tools. The moment payment clears, the manager is prompted to assign the job.
A technician gets the task. The customer gets a confirmation. The work moves forward.
This is the part most M-Pesa Payment Integration in Kenya providers ignore. But it is the part that actually grows your business.
Step Six — The Record
Every step is recorded. The conversation. The invoice. The payment. The job. The completion.
At any moment, anyone can see the full history. No one has to ask “did they pay?” or “who is handling this?”
That is the whole point. M-Pesa Payment Integration in Kenya should not just confirm money. It should move work forward.
Real Scenarios From Kenyan Businesses
Let me make this concrete. Here is how different businesses use Zivo.co.ke.
The Salon Owner in Nakuru
A salon owner handles bookings through WhatsApp. Clients book, confirm, and pay deposits via M-Pesa.
Before integration, she tracked everything in her head. Deposits got forgotten. Double bookings happened.
Now every booking has an invoice. Every deposit is tracked via STK Push. Every appointment is assigned to a stylist. The M-Pesa Payment Integration in Kenya keeps everything in order.
She has not had a double booking in six months.
The Hardware Distributor in Nairobi
A hardware distributor sells to contractors across three counties. Orders come through WhatsApp. Payments come through M-Pesa. Deliveries go out daily.
Before, reconciliation took two days weekly. Now it takes thirty minutes. The M-Pesa Payment Integration in Kenya does the matching automatically.
He has also cut fraud. Every delivery is linked to a confirmed payment. Nobody can claim a delivery that was never paid for.
The Cleaning Company in Mombasa
A cleaning company serves 40 commercial clients. Each pays monthly. Each has a different rate.
Managing this manually was chaos. Invoices went out late. Payments came in late. Some clients were never billed at all.
With Zivo.co.ke, recurring invoices go out automatically. Reminders are automatic. Payment tracking is automatic.
Revenue went up 22 percent in the first quarter. Not because they got new clients. Because they stopped losing money they had already earned.
The Solar Installer in Kisumu
A solar installer quotes jobs, collects deposits, and installs systems. Each job involves a deposit, a balance payment, and a scheduled installation.
Before, deposits were sometimes collected without installation being scheduled. Or installations happened without the balance being paid.
Now the M-Pesa Payment Integration in Kenya links everything. Deposit received. Installation assigned. Balance invoiced. Payment tracked. Completion recorded.
The owner says he now sleeps better. That is the real return on investment.
Why This Matters for Growing Businesses
Small businesses in Kenya face a specific trap. Growth brings more customers. More customers bring more transactions. More transactions bring more chaos.
WhatsApp threads pile up. M-Pesa messages pile up. Invoices pile up. Nobody knows the real position anymore.
This is the point where many businesses stall. They cannot scale because they cannot see.
The M-Pesa Payment Integration in Kenya breaks that ceiling. Every transaction has a home. Every payment has a status. Every job has an owner.
You can hire more staff without losing control. You can open another branch without losing visibility. You can grow without drowning.
Research shows that businesses in emerging markets that adopt integrated digital tools see revenue growth of up to 30 percent. That growth comes from eliminated waste, faster collections, and better decisions.
M-Pesa Payment Integration in Kenya delivers all three.
Compliance, eTIMS, and the KRA Question
Kenya’s tax landscape is changing fast. KRA now requires all businesses to issue electronic tax invoices through eTIMS.
From January 1, 2026, KRA validates every income and expense entry in tax returns against e-invoicing data.
This means your payment records must align with your invoices. Every shilling must be traceable.
KRA now cross-checks M-Pesa Till and Paybill collections against VAT returns, income tax returns, turnover tax, and withholding tax. If your M-Pesa sales do not match what you declare, a tax notice is almost guaranteed.
The M-Pesa Payment Integration in Kenya must help, not hinder, compliance.
Zivo.co.ke generates structured invoice records. It links payments to invoices. It maintains clean audit trails.
When KRA asks questions, you have answers. That is worth a lot.
Uptake of eTIMS has been slow. Many firms are still struggling. Zivo.co.ke simplifies this. Invoicing and payment tracking happen together. Compliance becomes a byproduct of good operations. This is the value of a proper M-Pesa Payment Integration in Kenya.
Security and Trust
Money software must be secure. That is non-negotiable.
Daraja 3.0 includes Security APIs. They enhance fraud detection, prevention, and identity verification.
Zivo.co.ke protects payment data with access controls. Only authorised staff can view or act on payment information. Every action is logged.
Approval workflows add another layer. No single person can move large sums alone. That protects against both fraud and honest mistakes.
For business owners, this peace of mind is worth the subscription alone. A secure M-Pesa Payment Integration in Kenya is essential infrastructure.
The Zivo.co.ke Difference
Zivo.co.ke stands apart because it was built for Kenya, not adapted to it.
It speaks M-Pesa natively. It speaks WhatsApp natively. It understands how local businesses actually operate. The M-Pesa Payment Integration in Kenya from Zivo fits the local reality.
Its design is simple. Staff learn it in minutes. Owners see value on day one.
It scales with you. Start with basic payment tracking. Add approvals later. Add multi-branch visibility as you expand.
Nothing is forced. Everything is modular. You grow at your own pace.
Common Questions Kenyan Business Owners Ask
Does it work without internet?
Yes. Zivo.co.ke handles intermittent connectivity gracefully. Transactions sync when connection returns. The M-Pesa Payment Integration in Kenya keeps working.
Can my staff use it without training?
Yes. If they can use WhatsApp, they can use Zivo.co.ke. The interface is that familiar.
Does it integrate with my bank?
It focuses on M-Pesa, which is where most Kenyan business payments happen. Bank integration continues to expand.
What if I have multiple branches?
Zivo.co.ke handles multi-branch operations with consolidated visibility. You see everything. Your branch managers see their own.
Is my data safe?
Yes. Access controls, encryption, and audit logs protect your information.
Do I need a developer to integrate?
No. Zivo.co.ke handles the M-Pesa Payment Integration in Kenya for you. You do not need to write a single line of code.
Empowering Your Business with Zivo.co.ke
The M-Pesa Payment Integration in Kenya is not a luxury. It is basic infrastructure for any business that wants to survive and grow.
Zivo.co.ke gives you that infrastructure without complexity. It gives you visibility without spreadsheets. It gives you control without hiring a finance department.
By adopting Zivo.co.ke, you are choosing to stop losing money to blind spots. You are choosing to know exactly where you stand. You are choosing to grow with confidence.
M-Pesa Payment Integration in Kenya from Zivo.co.ke transforms how you operate. It turns chaos into clarity.
In a market as competitive as Kenya’s, that edge matters. Every shilling recovered is a shilling reinvested. Every hour saved is an hour spent growing.
Embracing Zivo.co.ke is a practical step towards a stronger, more organised, and more profitable business. The best M-Pesa Payment Integration in Kenya is one that works the way you do.